


 Free Financial Statements Template
If you’re creating a cash flow statement for the first time, the difficult part usually isn’t the math. It’s knowing what belongs in it.
You may already have collected customer payments, paid payroll and supplier bills, bought equipment, made a loan payment, or put more of your own money into the business. But where should each of those transactions go, and how do you know the final number is right?
That’s where I have seen most beginners get stuck.
In this guide, I’ll walk you through how to create a cash flow statement step by step using a simple business example so you can follow the same process with your own numbers.
What is a cash flow statement?
A cash flow statement shows where cash came from, where it went, and how much your business had left at the end of a specific period, such as a month, quarter, or year.
It clearly organizes those cash movements into three parts:
| Cash flow activity | What it covers | Common examples |
| Operating activities | Cash from running the business | Customer payments, payroll, rent, supplier payments |
| Investing activities | Cash used to buy or sell long-term assets | Equipment, vehicles, property |
| Financing activities | Cash received from or paid to owners and lenders | Business loans, owner contributions, loan repayments |
Together, these three sections help explain why your cash balance increased or decreased during that period and whether that change came from normal operations, investing, or financing.
Here, I’d make one thing clear that cash flow and profit don’t always move together.
For example, you may record a sale before the customer actually pays you. That sale can affect your revenue or profit before the cash reaches your business.
So even if your business is profitable, your available cash may tell a different story.
For a deeper explanation, see our guide to cash flow vs. profit.
How to create a cash flow statement in 6 steps?
Now that you know what a cash flow statement is, the next step is to build one from your own records.
Before you start, choose the period you want the statement to cover, such as a month, quarter, or year. Then gather your bank statements, account balances, payment and expense records, loan details, and any records of asset purchases, sales, or owner contributions.
Make sure all the balances and transactions you use belong to the same reporting period. If you’re creating a January cash flow statement, use balances and transactions from January 1 through January 31.
Here, I’ll use Clearview Cleaning as an example throughout the steps so you can see where each number comes from and how the statement comes together.
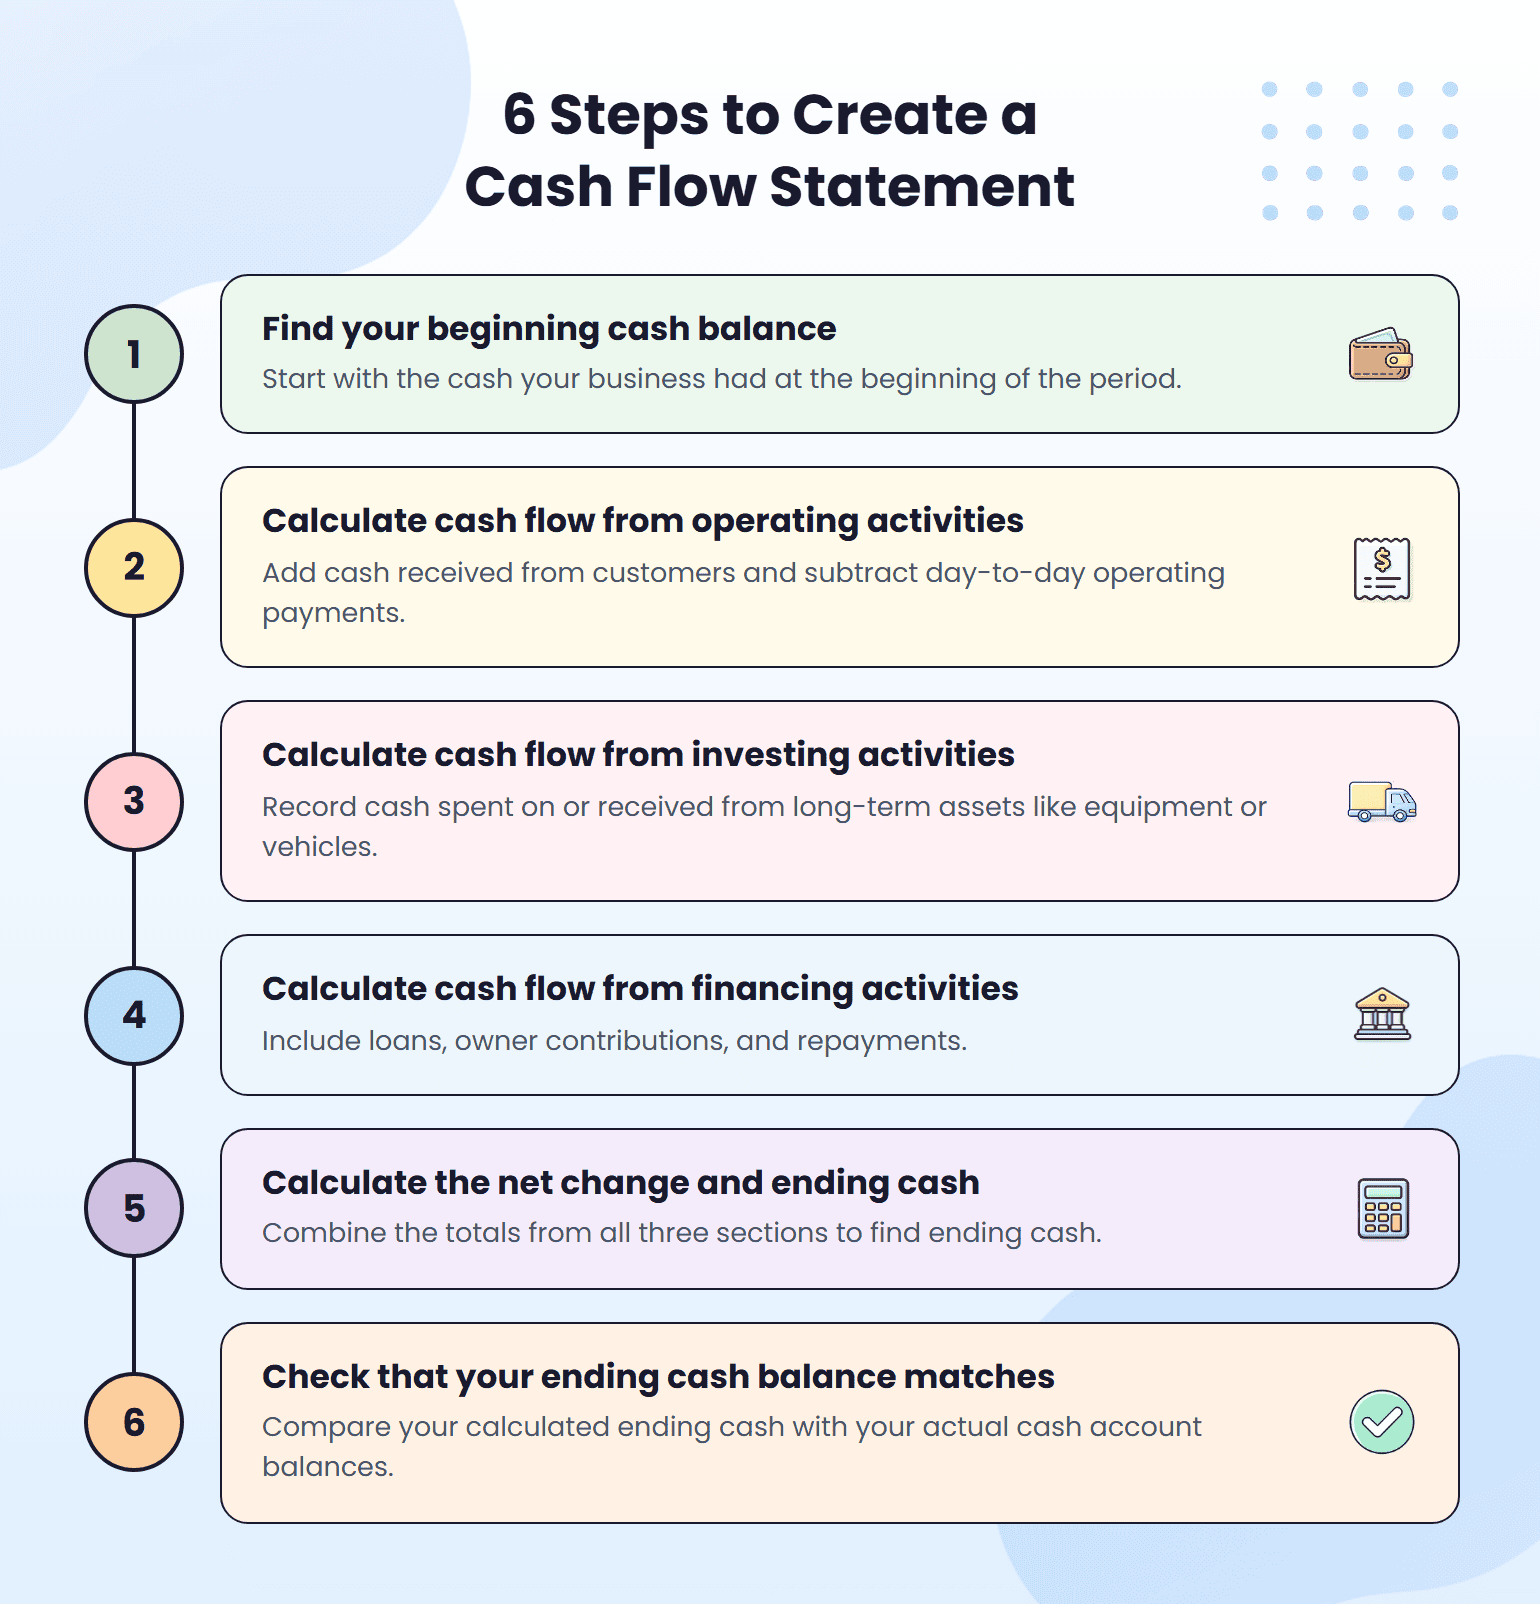
Step 1: Find your beginning cash balance
Start with the cash your business had at the beginning of the reporting period.
Suppose Clearview Cleaning started January with:
- $8,000 in its checking account
- $2,000 in its savings account
Its beginning cash balance would be:
$8,000 + $2,000 = $10,000
If you’ve already prepared a cash flow statement for the previous period, you can usually use its ending cash balance as the starting balance for the new one.
If this is your first statement, check the balances in your business checking, savings, and any petty cash you keep at the start of the period.
Don’t include unpaid customer invoices or other money you expect to receive later.
Step 2: Calculate cash flow from operating activities
Next, calculate the cash that came in and went out through your normal business operations.
For a small business, this usually includes customer payments and cash paid for payroll, rent, supplier bills, utilities, and other day-to-day expenses.
There are two ways to calculate cash flow from operating activities:
- Direct method: Uses the cash you actually received and paid.
- Indirect method: Starts with net income and adjusts for non-cash items and changes in working capital, such as accounts receivable, inventory, and accounts payable.
Both methods should arrive at the same net cash from operating activities. The difference is how you calculate that number.
If you’re unsure which method to use, check our guide to direct vs. indirect cash flow.
For Clearview, I’ll use the direct method because it’s easier to follow when you’re creating a cash flow statement for the first time.
Using the direct method
With the direct method, start with the cash your business actually received during the reporting period.
During January, Clearview collected:
Cash received from customers = $25,000
Suppose Clearview also completed a $2,000 cleaning job in January, but the customer won’t pay until February. Don’t include that $2,000 in January because the cash hasn’t been received yet.
The same rule works the other way with advance payments. If a customer pays a deposit before you deliver the product or service, it counts as a cash inflow in the period when you actually receive the money.
Next, total the cash paid for normal business operations during the same period.
Clearview paid:
| Operating payment | Amount |
| Payroll | $12,000 |
| Rent | $2,500 |
| Cleaning supplies | $2,000 |
| Other operating costs | $1,500 |
| Total operating cash paid | $18,000 |
Now, subtract the cash paid from the cash received:
Cash received − operating cash paid = net operating cash flow
For Clearview, net cash from operating activities is:
$25,000 − $18,000 = $7,000
So Clearview generated $7,000 in cash from its normal business operations during January.
What if you use the indirect method?
If you use the indirect method, only the operating activities section changes.
Instead of listing cash received and paid, start with your net income for the period and adjust it for non-cash expenses and changes in working capital.
Typical adjustments include:
- Depreciation and amortization, which are added back because they reduce profit without using cash during the period.
- Accounts receivable, because some sales may have been recorded before customers paid.
- Inventory, because buying inventory can use cash before those goods are sold.
- Accounts payable, because some expenses may be recorded before the business actually pays them.
For example, if accounts receivable increases, some of the revenue included in net income has not yet been collected in cash. That increase generally reduces operating cash flow.
After making the adjustments, you arrive at:
Net cash from operating activities
Once you have that number, the rest of the process stays the same. Continue with the steps below.
Step 3: Calculate cash flow from investing activities
Next, identify any cash spent on or received from long-term business assets, such as equipment, vehicles, machinery, or property.
A simple way to separate these from operating expenses is to consider what the purchase is for and how long the business will use it.
For Clearview:
- Cleaning chemicals used on customer jobs are part of operating activities.
- A commercial cleaning machine expected to last several years is an investing activity.
The first is part of the normal cost of delivering the service. The second is a long-term asset the business will use over time.
During January, Clearview bought a commercial cleaning machine and paid $4,000 in cash.
So record:
Purchase of cleaning equipment = −$4,000
If your business sells equipment, a vehicle, property, or another long-term asset, the cash received from that sale would appear here as an investing cash inflow.
Only record the amount of cash actually paid or received during the period. If you purchased an asset but haven’t paid for it yet, there is no cash outflow to record yet.
Clearview had no asset sales during January, so:
Net cash from investing activities = −$4,000
Step 4: Calculate cash flow from financing activities
The next step is to identify cash that came from or went back to the people or organizations funding the business.
For a small business, this can include:
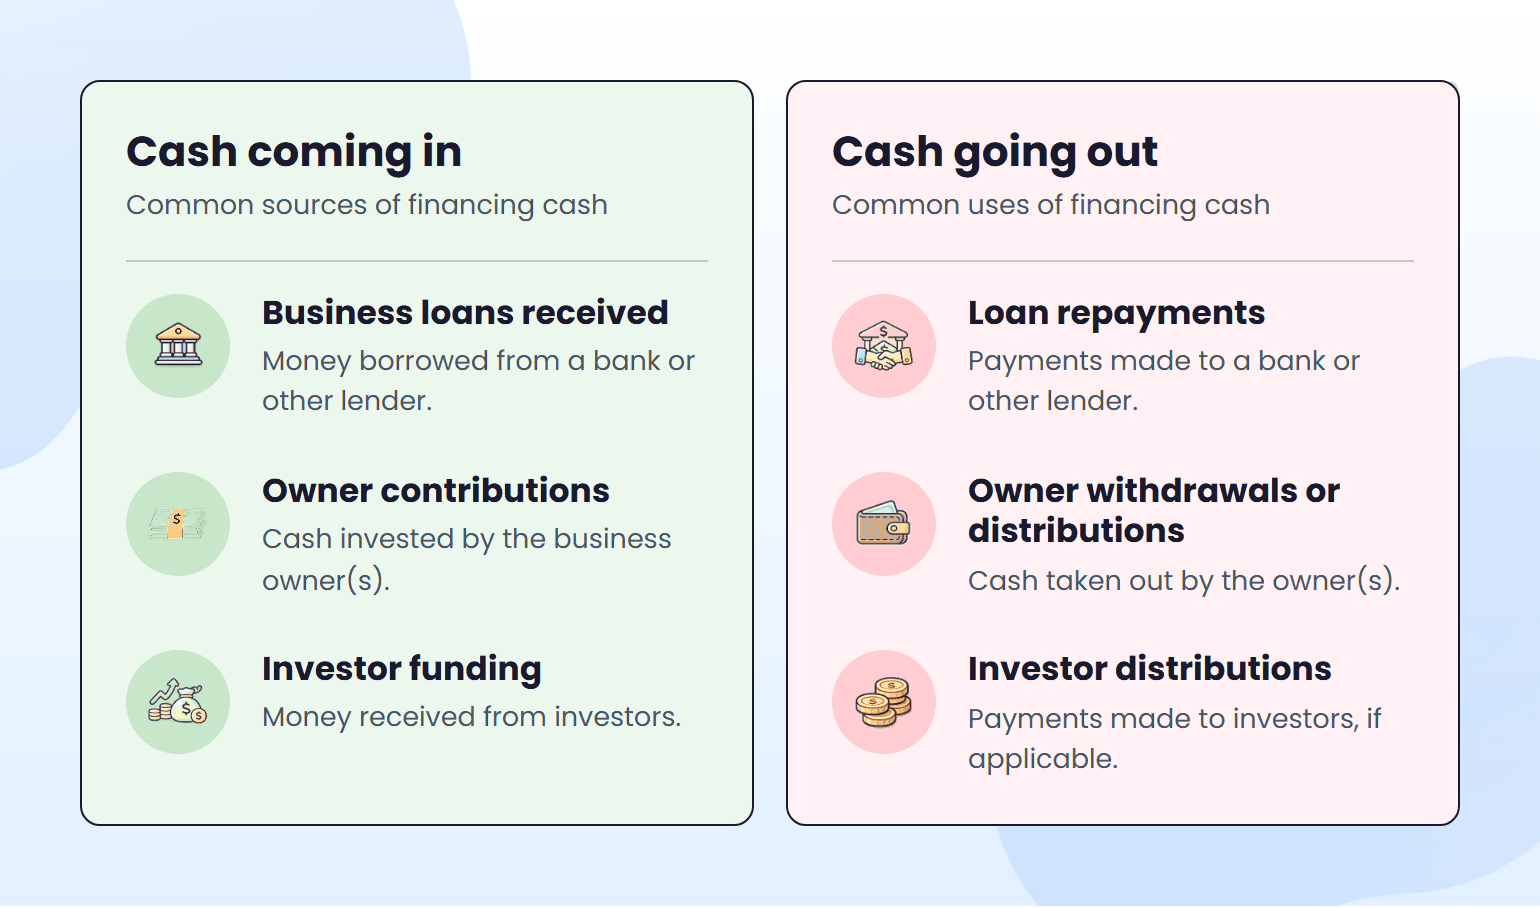
Suppose Clearview received a $5,000 business loan during January. Then record:
Business loan received = +$5,000
A loan increases the cash in your business account, but it is not revenue. The business did not earn that money from customers, and it will need to repay the lender. That is why the loan belongs under financing activities rather than operating activities.
The same applies if you put your own money into the business. An owner contribution increases business cash, but it is a financing inflow, not customer revenue.
If you made loan payments, check your loan statement to separate the payment into principal and interest. Under U.S. GAAP, principal repayments generally appear under financing activities, while interest paid appears under operating activities.
Your loan statement or amortization schedule should show how the payment is divided between principal and interest.
As with the earlier steps, only record cash actually received or paid during the reporting period.
Clearview made no loan repayments or owner withdrawals during January, so:
Net cash from financing activities = +$5,000
Step 5: Calculate the net change and ending cash
Now combine the totals from operating, investing, and financing activities to find how much your cash changed during the reporting period.
For Clearview:
| Activity | Net cash flow |
| Operating activities | +$7,000 |
| Investing activities | −$4,000 |
| Financing activities | +$5,000 |
Add them:
+$7,000 − $4,000 + $5,000 = +$8,000
So:
Net change in cash = +$8,000
This means Clearview’s cash increased by $8,000 during January.
Next, add that change to the beginning cash balance you calculated in Step 1:
Beginning cash + net change in cash = ending cash
For Clearview:
$10,000 + $8,000 = $18,000
So:
Ending cash balance = $18,000
Now, you have completed the main calculation for the cash flow statement. The next step is to make sure the ending cash balance you calculated matches the cash your business actually had at the end of the reporting period.
Step 6: Check that your ending cash balance matches
For Clearview, Step 5 gave an ending cash balance of: $18,000
Now compare that amount with the balances in the same cash accounts you included at the beginning of the period.
For example, Clearview started January with:
- Checking: $8,000
- Savings: $2,000
So when checking the January ending balance, it should compare the calculated $18,000 against the combined balance of checking and savings again.
If you include checking and savings at the beginning but compare the ending balance against checking only, the statement can appear wrong even when the transactions are correct.
Also watch for transfers between your own business accounts. Suppose Clearview moves $5,000 from checking to savings. The business has not gained or lost $5,000. The cash has simply moved between two accounts.
If both accounts are included in your cash balance, do not record that transfer as a new cash inflow or outflow.
If the balances still don’t match, don’t change the ending number just to make the statement work. Go back through the transactions and look for the difference.
Common things to check include:
| If you notice this | Check for |
| Ending cash is too high | Unpaid invoices accidentally included as cash received |
| Ending cash is too low | Missing customer payments or other cash inflows |
| Cash appears twice | Transfers between your own business accounts counted as new cash |
| Financing total looks wrong | Missing loans, owner contributions, or loan repayments |
| Investing total looks wrong | Missing equipment or other long-term asset purchases |
| The difference matches one payment | A transaction recorded twice or in the wrong period |
If the balances in Clearview’s cash accounts total $18,000 on January 31, the statement reconciles.
At this point, Clearview’s January cash flow statement is complete.
You’ve now calculated each part of the statement separately. The easiest way to check that everything fits together is to put those numbers into one complete cash flow statement.
Here’s what Clearview’s statement looks like.
Cash flow statement example for a small business
Using the numbers from the steps above, Clearview Cleaning’s completed January cash flow statement:
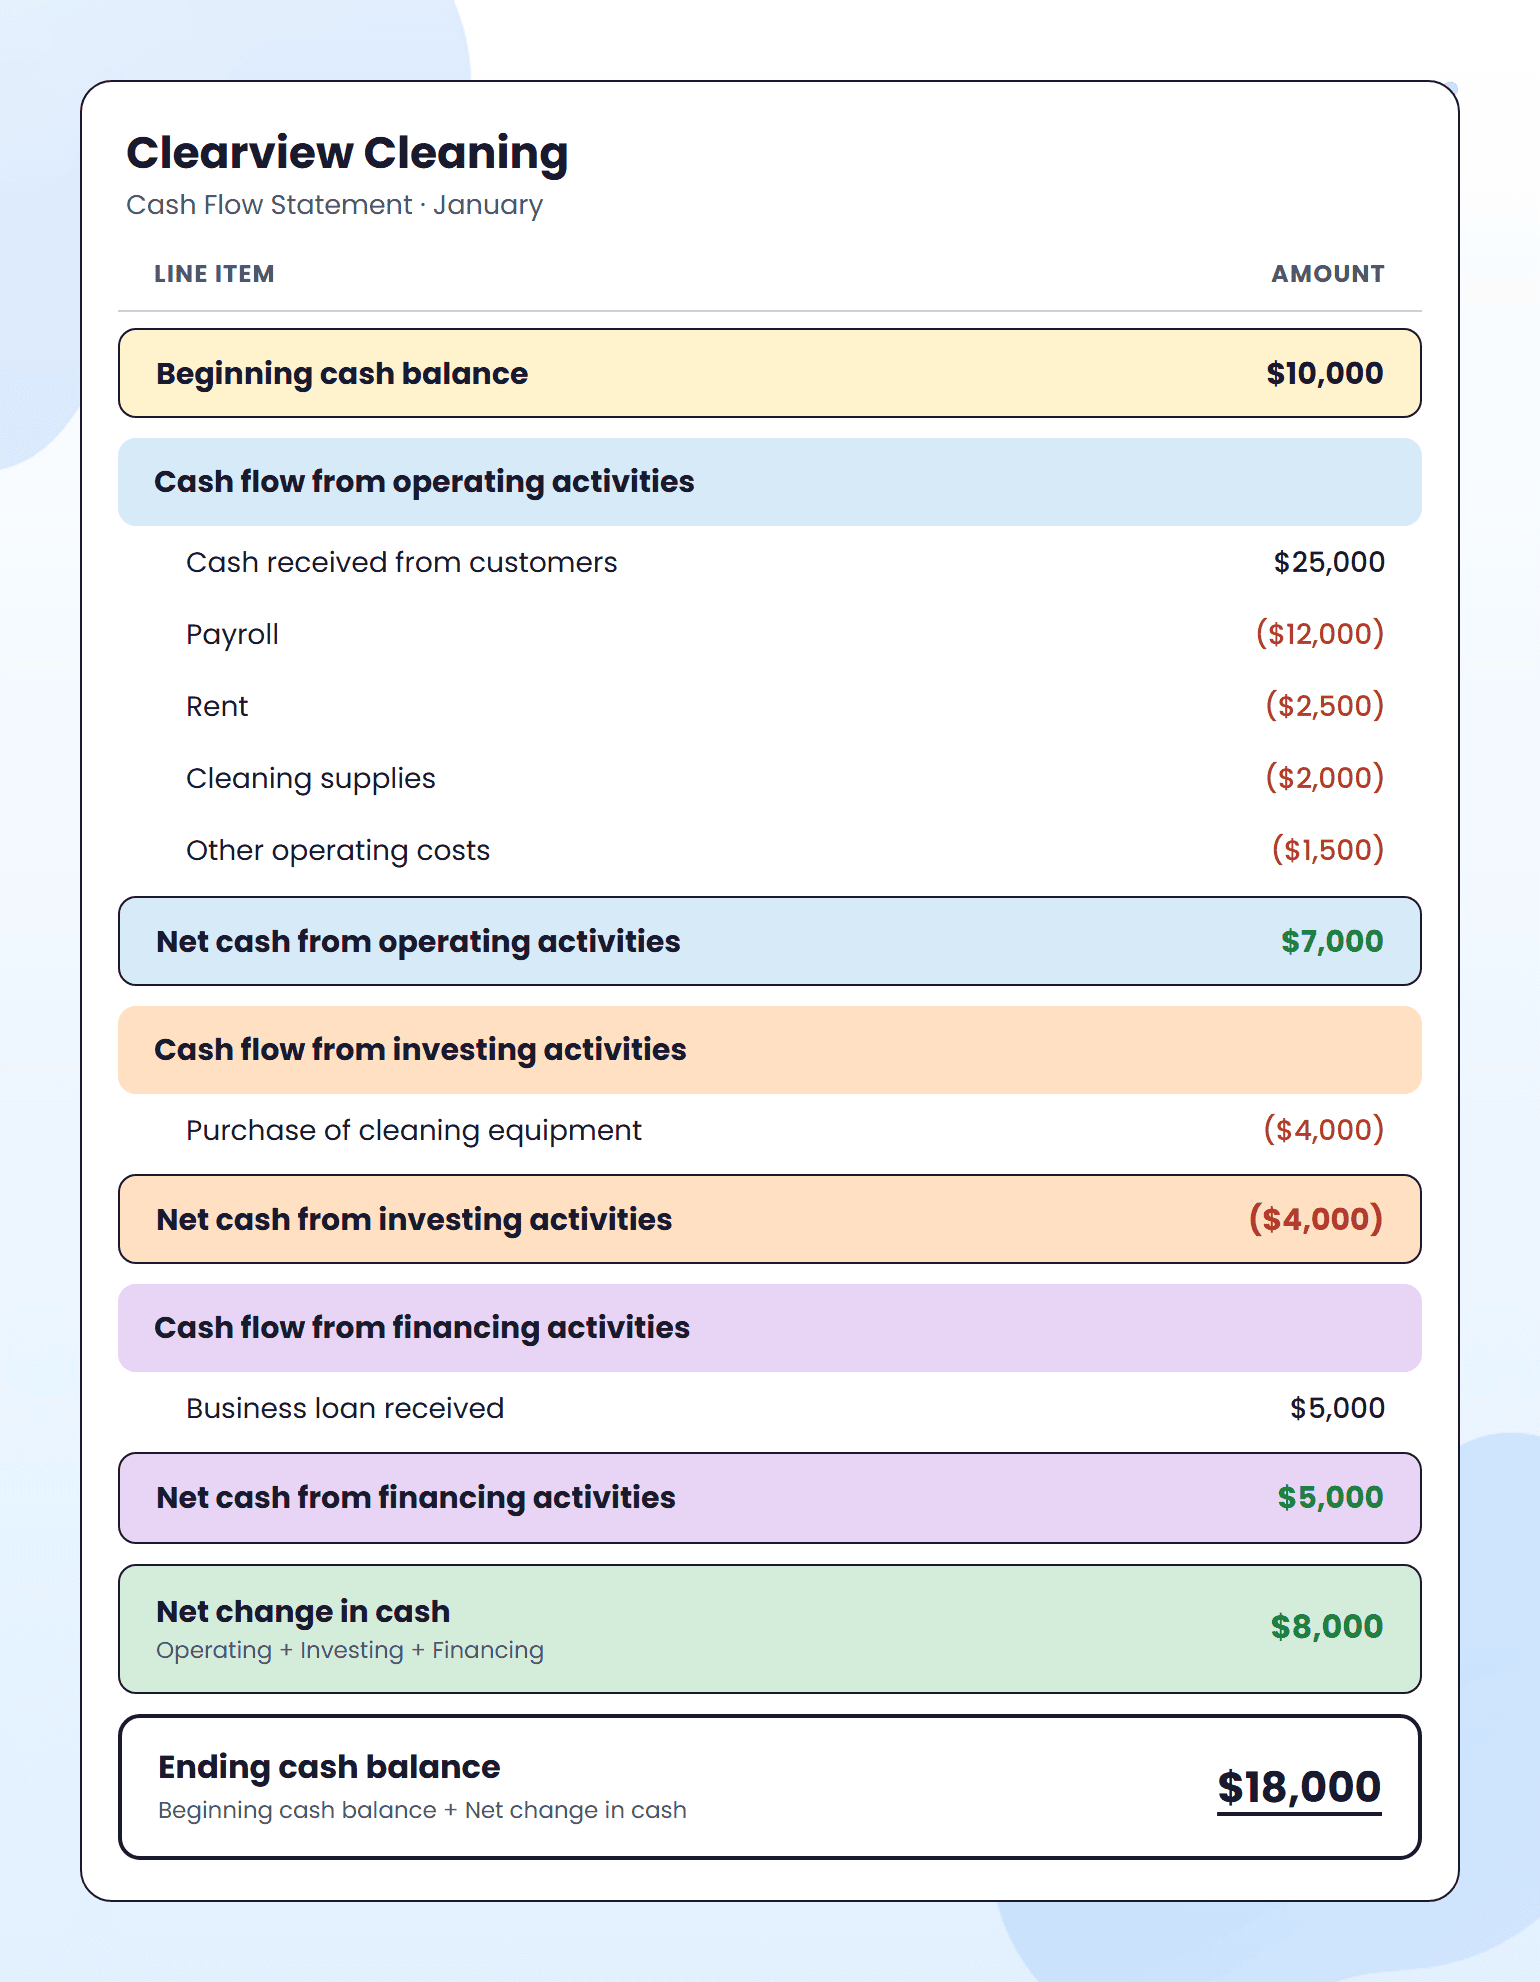
You can verify the ending balance with the same calculation from Step 5:
$10,000 beginning cash + $8,000 net change = $18,000 ending cash
Notice that Clearview’s cash increased by $8,000, but that increase did not come entirely from its normal business operations. It generated $7,000 from operations, spent $4,000 on equipment, and received another $5,000 through financing.
That is why separating cash into operating, investing, and financing activities matters.
You can use this same structure in Excel or Google Sheets and replace Clearview’s figures with your own business numbers.
Keep your cash flow statement useful
Creating one cash flow statement gives you a clear picture of what happened during that period. The bigger value comes from preparing it consistently and comparing the results over time.
That can help you see whether cash from normal operations is getting stronger, whether the business is relying more on outside funding, or whether a large purchase caused a temporary change in cash.
And if you’re moving from reviewing past cash flow to planning what happens next, especially for a business plan or upcoming decisions, Upmetrics’ financial forecasting tool can help you build projected cash flow alongside your profit and loss and balance sheet forecasts.
Create Your Cash Flow Statement
Project your cash inflows and outflows to understand your future cash position.

Frequently Asked Questions
How often should a small business prepare a cash flow statement?
Can I create a cash flow statement from my bank statements?
Can I prepare a cash flow statement without accounting software?
Do I need a cash flow statement or cash flow forecast for my startup?
What if my cash flow statement doesn’t match my bank balance?
Vinay Kevadia
Vinay Kevadiya is the founder and CEO of Upmetrics, the #1 business planning software. His ultimate goal with Upmetrics is to revolutionize how entrepreneurs create, manage, and execute their business plans. He enjoys sharing his insights on business planning and other relevant topics through his articles and blog posts. Read more