If you already know how to mow, the hard part of a lawn care business plan usually isn’t describing the service. It’s showing how the business will actually work.
- How many lawns can one person realistically handle?
- How tightly should customers be grouped?
- When does it make sense to hire help?
- And how do seasonal work and slower winter months affect the numbers?
That’s why I built this hypothetical example around Meadowline Lawn Care LLC, a one-person residential lawn care business in Cedar Hollow, Ohio, seeking an SBA-backed startup loan. The figures are illustrative, but the pricing, route strategy, staffing, seasonality, and financials support the same operating logic.
You can use it as a reference while drafting your own plan.
Executive Summary
Business name: Meadowline Lawn Care LLC
Location: Cedar Hollow, Ohio
Owner: Evan Carter
Business Structure: Single-member LLC
Meadowline Lawn Care is a one-person lawn care business launching in Cedar Hollow, Ohio, a suburb just north of Columbus. Evan Carter is the founder and will operate it himself.
The whole idea is to run one tight route instead of chasing lawns all over town. Regular mowing is how Meadowline wins a customer in the first place. Once a yard is on the weekly schedule, Evan adds the services that actually make money:
- Fertilizing and weed control
- Aeration
- Overseeding
- Spring and fall cleanups
Keeping customers close together means less time driving, more lawns done in a day, and more work sold to the people already on the route.
For the first year at least, this is a one-man operation. Evan will mow, sell, schedule, quote, and deal with customers himself. He has spent nine years on commercial crews, the last four running one, so he already knows how to plan a route, price a job, and keep customers happy.
Working solo at the start keeps costs low, which is what lets the business pay the loan even if the first season starts slow. Part-time seasonal help comes later, once the route is full enough to need it.
The target area has about 4,500 owner-occupied homes that fit the customer Meadowline is after. Reaching 125 regular customers by the end of Year 3 is under 3% of them. So the plan does not need to win the Columbus market. It just needs a solid pocket of customers across a few neighborhoods that sit close together.
Funding and Financial Outlook
The business is asking for a $55,000 SBA-backed loan from Cedar Hollow Community Bank, with Evan putting in $20,000 of his own money, which covers the full $75,000 needed to get going.
The money goes toward a commercial zero-turn mower and handheld tools, a trailer, a used truck, insurance, licensing, launch marketing, starting supplies, and cash to operate on. All of it fits what an SBA 7(a) loan can pay for: equipment, supplies, and working capital.
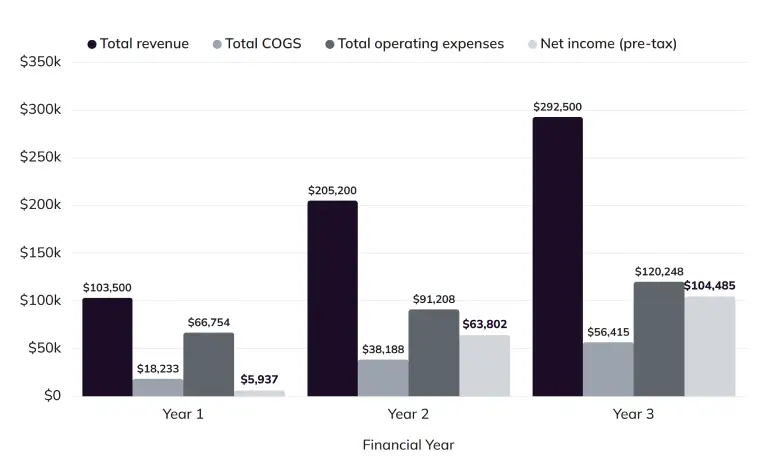
Revenue is expected to reach $103,500 in Year 1, $205,200 in Year 2, and $292,500 in Year 3. After owner pay, depreciation, and loan interest, pre-tax profit grows from $5,937 in Year 1 to $104,485 in Year 3.
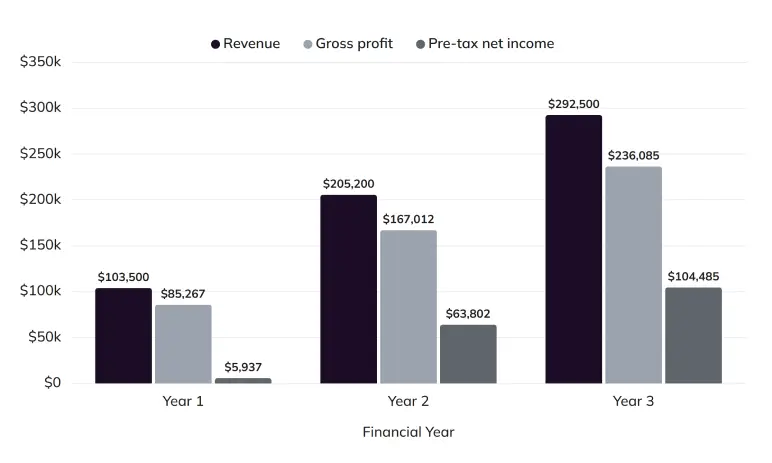
The strategy is simple. Build one route that is full, profitable, and easy to repeat, and prove it can cover the loan comfortably before taking on a second one.
Don’t spend weeks on your first draft
Complete your business plan in less than an hour
Company Overview
Meadowline Lawn Care is a brand-new single-member LLC, owned outright by Evan Carter, launching ahead of its first full spring season. It provides regular mowing and seasonal turf care for homeowners in Cedar Hollow and the surrounding streets.
The business runs out of a small rented storage unit near the route, with no office or storefront. That is because a lawn business lives on a tight map and a schedule people trust, not on walk-in traffic.
The LLC keeps personal and business money separate and gives customers and the bank a real company to deal with, and profits pass through to Evan’s personal taxes, so it’s cheap and simple to keep running.
The Operating Model
Underneath every decision is one rule: build one dense, profitable route before building a bigger company. It’s why Meadowline turns down lawns that sit too far out, grows by selling more to the customers it already has instead of stretching the map, and holds off on hiring until the route actually calls for it.
Recurring mowing is the base of the business, the weekly reason Evan is on a property at all, and the higher-margin seasonal work gets layered onto those same accounts. So the money grows as much from doing more for current customers as from signing new ones.
Starting Solo
Going solo is on purpose. It holds fixed costs down while the customer base fills in, and it lets Evan set the standard himself. Help comes on when the work is there, not before the money is. The near-term goal is deliberately small: prove this one route can run full, stay profitable, and carry the loan, and only then look at a second one.
First Three-Year Objectives
Here’s what the first three years are actually aiming at, and the targets that say whether it’s working:
| Objective | Target |
|---|---|
| Establish recurring route | 55 accounts by end of Year 1 |
| Reach near break-even | Year 1 |
| Expand recurring base | 95 accounts in Year 2; 125 in Year 3 |
| Maintain add-on service revenue | Roughly one-third of total revenue |
| Add seasonal labor | As route and add-on backlog approach capacity |
| Consider second route | Only after the first route is consistently profitable |
Market Analysis
Industry Context
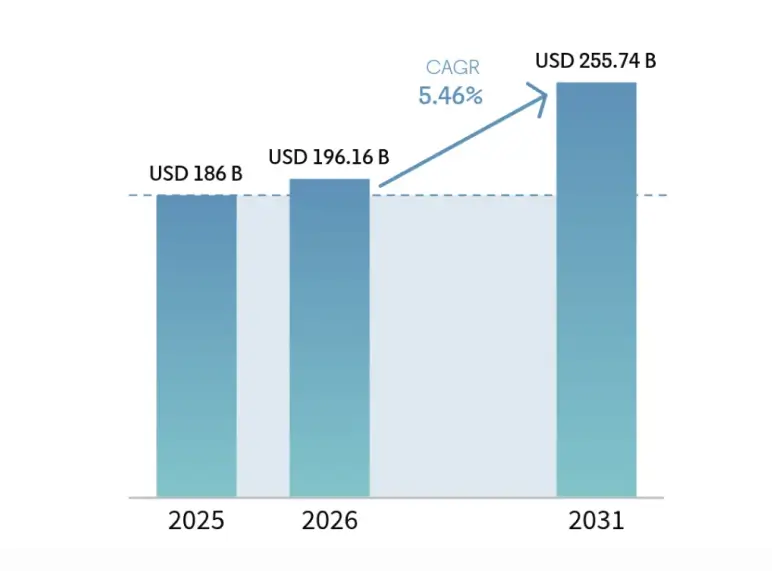
Lawn care sits inside the much larger U.S. landscaping-services industry. Its market size is expected to grow from $186 billion in 2025 to $196.16 billion in 2026.
Also, the National Association of Landscape Professionals reports:
- More than 1.4 million workers
- Approximately 692,777 landscaping-service businesses
That tells you the work is huge and spread across a lot of small operators, but it is not Meadowline’s market.
One person with one truck can only serve so many lawns within a short drive, so what matters here is local: who owns their home, how big the lots are, what people earn, and how close together they live. It helps that people care about this.
In a NALP survey, 95% of homeowners with a yard said keeping it looking good mattered to them.
Local Demand
Cedar Hollow is a stand-in name, so this plan uses real nearby suburbs north of Columbus as a guide rather than making up numbers.
- Delaware County had 95,340 homes in 2025, 78.5% of them owner-occupied, a median home value of $445,500, and 2,016 new home permits that year.
- Powell shows the higher-income end Meadowline expects to see, at 88% owner-occupied and a median household income of $195,495.
- Westerville has more than 15,208 households, 72.5% owner-occupied, and a median household income of $109,404.
Two physical facts drive the demand underneath those numbers:
- Quarter-acre lots: big enough to be a weekly chore, small enough to afford help with
- Dual-income households: short on time, willing to pay for a yard they never touch
Many of these neighborhoods also carry informal HOA-level upkeep expectations, which turns a well-kept lawn from a luxury into closer to an obligation. These customers shop on reliability, not price. What they’re really buying is not having to think about it.
Addressable Market
The real market is the owner-occupied homes inside the drivable cluster, about 4,500 single-family homes across the three to four target neighborhoods, most on conventional lots.
| Year | Recurring accounts | Penetration of 4,500 homes |
|---|---|---|
| Year 1 | 55 | 1.2% |
| Year 2 | 95 | 2.1% |
| Year 3 | 125 | 2.8% |
Year 3 needs roughly one home in every 36, tightly clustered. Meadowline doesn’t need to dominate Columbus or win a whole neighborhood; it needs a small share of the right homes, with comfortable headroom against the area’s capacity.
Target Customer
A homeowner roughly 35–65, in a detached suburban home, who’d rather pay for reliable lawn care than spend every weekend on it. Best prospects:
- Dual-income households and professionals with young families
- Older homeowners done maintaining the lawn themselves
- Homeowners burned by a cheaper operator that kept flaking out
They’re buying three things:
- Predictability: Serviced the same general day each week
- Convenience: One provider for mowing, fertilization, aeration, and cleanup, not four
- Appearance: A property that stays maintained without them managing it
Their behavior is what makes a concentrated area compound: they sign up in spring, renew year over year once happy, and respond to neighbors.
A tidy lawn with a small yard sign closes referrals faster and cheaper than any ad. Most enter through recurring mowing; the goal afterward is to grow annual revenue per customer by adding the services the yard already needs.
Competitive Analysis
Cedar Hollow already has many lawn-care options. Meadowline will compete with several types of alternatives rather than one dominant provider.
| Alternative | Strength | Common Limitation | Meadowline’s Position |
|---|---|---|---|
| Low-cost solo mower | Low price | Narrow service menu; availability may vary | Reliable recurring schedule plus seasonal services |
| Small multi-crew company | More capacity | Higher overhead; changing crews | Owner accountability and tighter route |
| Large regional provider | Systems and brand recognition | Less personal; services may be fragmented | One local relationship for maintenance and turf care |
| DIY homeowner | No contractor fee | Time, equipment, storage, physical effort | Convenience and predictable service |
The company’s real edge is the combination: a tight route, the same service day every week, the owner on every lawn, and a fuller menu than most mow-only operators offer.
Anyone can match the price on one lawn. What they cannot match is how little it costs to service a lawn thirty seconds from the last stop.
Services and Pricing
Meadowline is a recurring-service business, not a mowing business. Mowing is the way in: it creates a weekly relationship with the customer and a predictable, routable schedule. But the margin lives in the seasonal and recurring add-ons.
The strategy is simple: win the mowing account, then sell higher-value work into a yard the crew already knows and visits every week.
Service menu
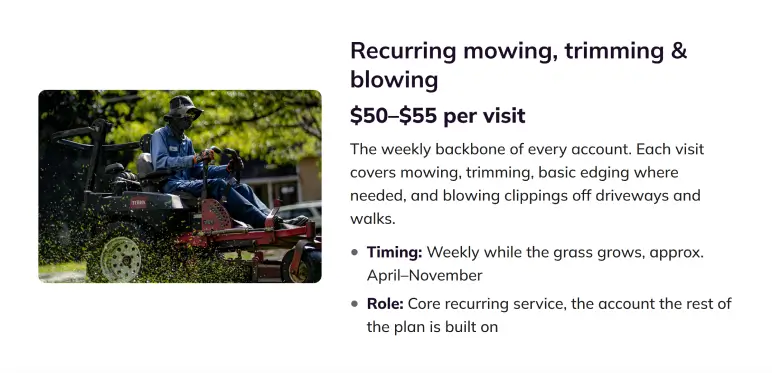
A mowing visit covers mowing, trimming, basic edging where needed, and blowing clippings off driveways and walks. Everything else is built on top of that weekly relationship.
Core recurring service
The weekly backbone of every account, and the service that opens the door to all the others.
Seasonal and recurring add-ons
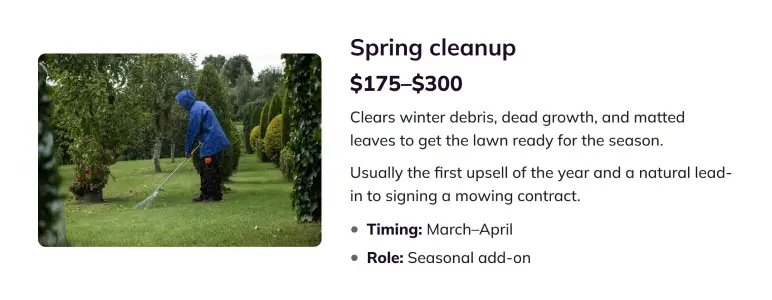
(1) Spring cleanup
Clears the winter’s debris and dead growth so the lawn starts the season healthy, often the first upsell.
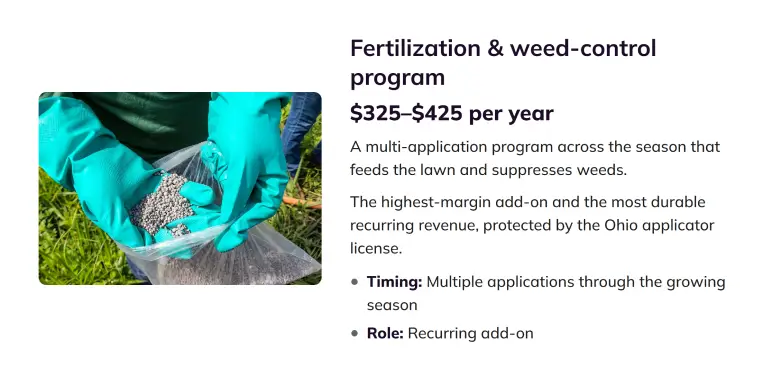
(2) Fertilization & weed-control program
The most durable recurring revenue in the plan, and the hardest for competitors to copy.
(3) Aeration & overseeding
Thickens the turf for a visibly healthier lawn — easy to show, and easy to sell.
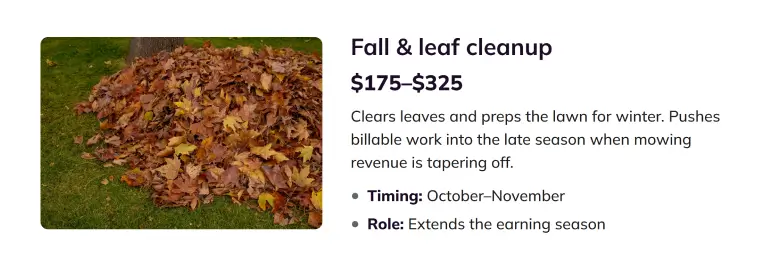
(4) Fall & leaf cleanup
Pushes billable work into the late season, keeping revenue going as mowing winds down.
How we quote
No two properties price the same. Every quote reflects lot size, obstacles, slope, gates, materials, and where the home sits on the route. A yard that’s easy to reach on an existing loop costs less to serve than an outlier across town.
Most customers get weekly service while the grass is growing, and that’s deliberate. Meadowline doesn’t take one-off “call me when it’s long” mowing, because unpredictable visits break route planning and erode the margin on every other stop that day. Weekly accounts keep the schedule tight and the trucks full.
The add-on strategy
Mowing opens the door; the add-ons carry the profit. Aeration, overseeding, and cleanups are sold to existing mowing customers first, because the yard is already known, the relationship already exists, and there’s no cost to find the customer again.
A fertilization program sold to a current account is close to pure margin on top of a route we’re already driving. This is why Meadowline treats every mowing account as the beginning of a relationship, not the whole of it.
Revenue model
Add-on revenue isn’t a single hopeful growth number. It’s built from the bottom up, from how many jobs we expect to sell and what each one costs. That makes it checkable, and it means the forecast can be updated the moment real sign-up rates or prices come in differently.
The build, by service:
| Service | Year 1 | Year 2 | Year 3 |
|---|---|---|---|
| Fertilization programs | 30 × $400 = $12,000 | 55 × $400 = $22,000 | 80 × $400 = $32,000 |
| Aeration & overseeding | 25 × $320 = $8,000 | 50 × $320 = $16,000 | 75 × $320 = $24,000 |
| Spring cleanups | 25 × $240 = $6,000 | 50 × $240 = $12,000 | 60 × $250 = $15,000 |
| Fall cleanups | 40 × $250 = $10,000 | 80 × $250 = $20,000 | 116 × $250 = $29,000 |
| Total add-on revenue | $36,000 | $70,000 | $100,000 |
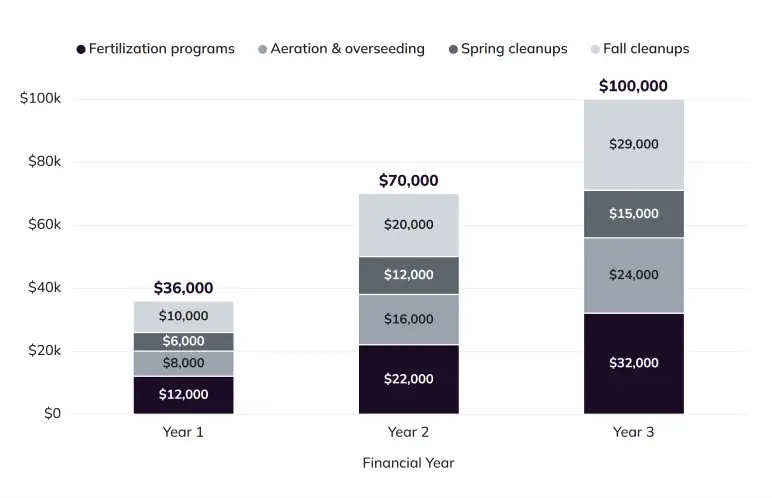
That puts total add-on revenue at $36,000 in Year 1, $70,000 in Year 2, and $100,000 in Year 3 with fertilization and fall cleanups as the primary engines (the chart above shows the trajectory).
The growth assumes the mowing base expands enough to sell into; if it grows faster or slower, every line above updates with it.
The Economics of a Dense Lawn-Care Route
Pricing decides what Meadowline can earn on a job. The route decides how much of that it actually keeps.
Every minute spent driving between lawns is a minute that is not getting paid, so on a one-person route the real question is not how many customers there are, it is how much of the day is spent actually working on lawns.
Here are two versions of the same work day.
| Factors | Scattered route | Dense route |
|---|---|---|
| Mowing stops per day | 18 | 26 |
| Average mowing ticket | $52 | $52 |
| Daily mowing revenue capacity | $936 | $1,352 |
| Difference | +$416 per day |
Over a five-day week, that is more than $2,000 in extra work that could be done. Over a 32-week season, it is about $66,000 of mowing capacity.
That is not the sales forecast, since the schedule also needs time for rain days, treatments, quotes, maintenance, and paperwork. It is the reason Meadowline will not take every customer just to pad the count.
Revenue per Customer
Route density is only half of the equation.
A mow-only customer paying $50 across 32 visits is worth about $1,600 a year. The same customer who also buys the seasonal work is worth a lot more from the exact same address.
| Service | Illustrative annual revenue |
|---|---|
| Mowing | $1,600 |
| Fertilization | $400 |
| Spring cleanup | $200 |
| Aeration and overseeding | $350 |
| Fall cleanup | $250 |
| Total | $2,800 |
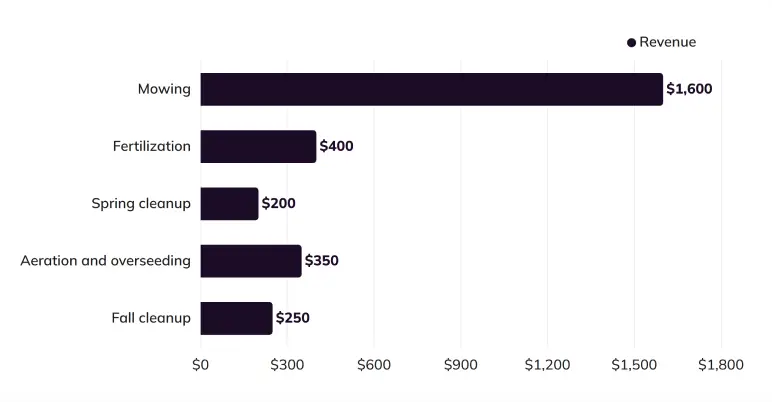
That customer brings in about 75% more a year without adding a single minute of driving.
So Meadowline tracks three things together, not just the customer count: how many customers there are, how close they sit, and how much each one spends in a year.
Marketing and Sales Strategy
Marketing has one main job: tighten the route. The aim is mostly to win the neighbors of existing customers, because the lawn next door brings in money with almost no extra driving.
The primary channels are yard signs at finished jobs, door hangers to nearby homes, customer referrals, a Google Business Profile, tightly targeted local search ads, and a spring push that sells mowing and the fertilization program together.
Keeping customers matters just as much as finding them. A customer who renews costs nothing in advertising, quoting, or route reshuffling. So a steady service day, a heads-up when weather moves things, and a renewal check-in each year are all part of how the business grows.
Year 1 Customer Acquisition Plan
The 55-account Year 1 target is a planning goal, not customers already signed. What matters more than the total is whether each channel brings customers inside the route.
Ten customers on streets Meadowline already mows are worth more than twenty scattered across town.
| Channel | Year 1 account target |
|---|---|
| Door hangers and yard signs in target neighborhoods | 20 |
| Customer and neighbor referrals | 15 |
| Google Business Profile and local search | 10 |
| Spring promotions and other local leads | 10 |
| Total year-end recurring accounts | 55 |
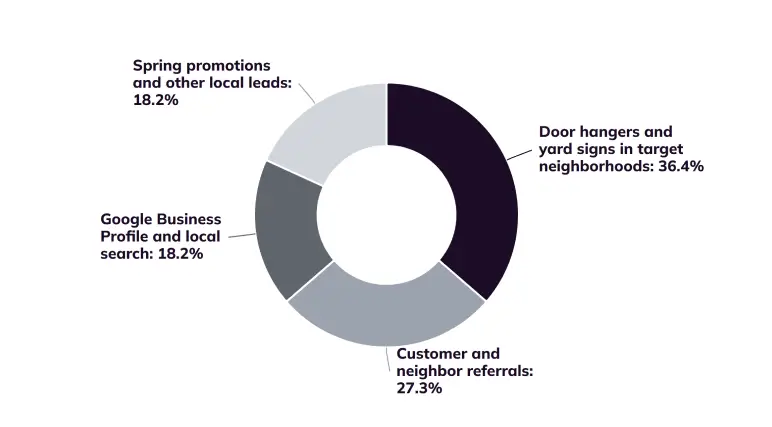
The mix can change as actual acquisition data becomes available. The more important thing is whether each channel adds customers inside the desired route.
A channel generating 20 distant customers may be less valuable than one generating 10 customers on streets Meadowline already services.
Need to present your numbers clearly? Upmetrics makes it easier to design professional visuals that show your numbers effectively and make your plan stand out.
Operations Plan
A dense route only pays off if it’s run on a disciplined schedule. Operations are built around a fixed weekly rhythm rather than reacting as calls come in. The same discipline that makes the route profitable is what makes the service reliable.
Operating Rhythm
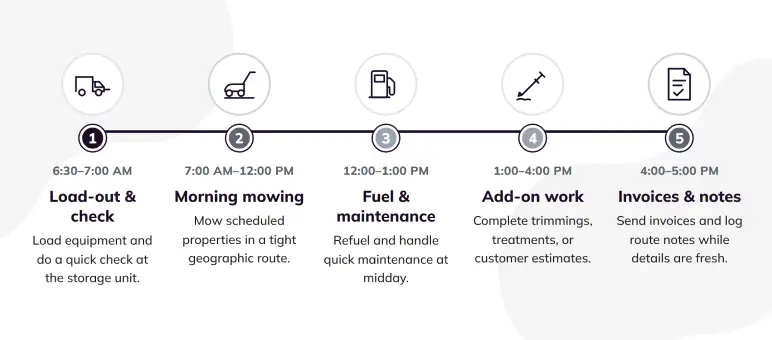
In season, the workweek runs Monday to Friday, roughly 7:00 a.m.–5:00 p.m.
- Fixed day per neighborhood: A given street is always mowed on the same day (say, Tuesday), so customers can rely on it and the route stays compact.
- Geographic order: Stops run by location, never by sign-up order.
- Saturday held as a buffer: Reserved for weather catch-up, larger seasonal jobs, aeration, and equipment work. No recurring mowing route is scheduled on it, so one rainy week can’t push every customer permanently behind.
Scheduling and Route Acceptance
New accounts are slotted into the existing day for their neighborhood, which preserves route density automatically. New pockets are built out fully before scattering single accounts elsewhere.
When a lead sits materially outside the route, there are three options in order of preference:
- Quote a premium that covers the extra travel time,
- Hold the lead until nearby demand develops, or
- Decline the account
This may hold down top-line customer count in the short term. But it protects the economics of the route — the largest controllable risk in the business.
A Typical Day
Billing
Customers are billed monthly on Net 15 terms by card or ACH through the invoicing app. Recurring customers are encouraged to keep payment on file or use automatic payment. Monthly billing smooths cash flow and keeps collection off the truck.
Capacity and Hiring
A solo route has a hard ceiling, and knowing where it sits is the difference between growth and burnout.
- On paper: ~26 stops/day × 5 days ≈ 130 weekly mowing slots.
- In practice: The week also absorbs treatments, cleanups, rain delays, estimates, and admin. So the real ceiling is 110–125 recurring accounts.
- Year 3 ends at 125: The point where labor, not demand, becomes the constraint.
Seasonal help is pre-funded and scales with the route: 300 hours in Year 1, 700 in Year 2, 1,100 in Year 3, modeled at $18/hour.
The trigger to hire is operational: when mowing consistently spills into Saturdays or backlog runs high for three-plus weeks, the helper comes on before quality slips — about a month ahead of the ceiling, since training during peak overload is how retention breaks at the worst time.
Equipment
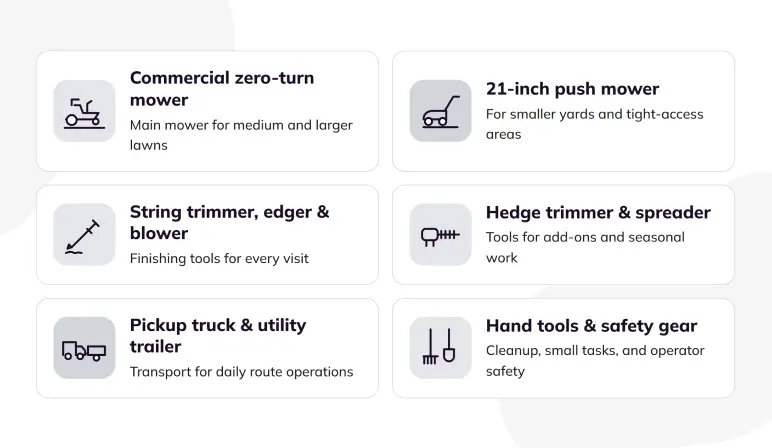
Equipment is bought based on what earns, not what’s cheapest:
Maintenance and downtime plan
Evan will inspect equipment before each route, clean and sharpen blades regularly, and schedule servicing during lighter work periods. Meadowline will maintain spare blades, belts, and other frequently replaced parts.
For major breakdowns, the business will use a local repair provider or short-term rental equipment to avoid missing scheduled customer visits.
Licensing and Compliance
Meadowline operates with:
- An Ohio LLC registration, general liability insurance, and commercial auto coverage;
- All payroll and workers’ compensation obligations that apply once seasonal help is used; and
- An Ohio commercial pesticide and fertilizer applicator license through the Ohio Department of Agriculture, required for the fertilization and weed-control program.
That applicator credential is what lets Meadowline legally offer its highest-margin service and it’s the barrier that keeps most mow-only competitors out of it. Treatment records, product labels, application documentation, and customer notices are maintained alongside it.
Risk & Mitigation
A one-person business has real risks, and a lender will think about them whether or not the plan names them. So here they are, with how each is handled.
(1) Losing the owner to injury or illness.
Since the owner does all the work, his being out stops revenue. So disability insurance covers the loan and living costs, and a trained helper plus a backup operator keep core lawns mowed through a short absence.
(2) A bad weather year.
Rain drives mowing up while drought or an early frost cuts it, so weather-independent add-on revenue and the cash reserve carry a soft season, and the forecast assumes a normal year rather than a peak one.
(3) Rising fuel and supply costs.
Gas, fertilizer, and parts can climb, but they’re a small share of a high-margin base, and annual price step-ups (50-55 per visit) pass real increases through.
(4) Growing too fast.
Taking on more lawns than one route can serve well is the biggest risk the owner controls, handled by a pre-funded hiring trigger that adds help before service quality slips.
Seasonality and cash-flow management
Even a perfectly run route stops earning when the grass stops growing.
In central Ohio, mowing revenue is concentrated in roughly eight months (April–November), while fixed costs, such as the loan payment, insurance, storage, software, bookkeeping, and living expenses, run all twelve.
Seasonality is therefore engineered as a cash-flow problem, not just a calendar fact.
| Period | Expected activity | Cash-flow role |
|---|---|---|
| Jan–Feb | Minimal lawn revenue | Preserve working capital; renewals and planning |
| Mar–Apr | Spring cleanup, early treatments | Revenue begins before full mowing season |
| May–Aug | Peak mowing and treatments | Main cash-building period |
| Sep–Oct | Mowing, aeration, overseeding | High-value add-on period |
| Nov | Leaf cleanup and late mowing | Extends the earning window |
| Dec | Minimal base-case revenue | Operate from retained seasonal cash |
Because the gap is predictable, it’s funded on a schedule rather than scrambled for in January. Four mechanisms:
- A $27,000 working-capital reserve, sized to carry fixed costs and the loan through the first winter and a slow ramp. (The opening balance sheet shows $32,500 in cash because it also holds funds for one-time Year 1 costs not yet paid at launch.)
- Program and monthly billing, which spread revenue more evenly than pure per-visit charging.
- A shoulder-season tail of leaf removal and light snow work for existing customers; backfilling part of the off-season without expanding the map.
- A fixed holdback from every peak-season invoice into a separate reserve, funding the known winter gap continuously through the busy months.
This is where profit and cash diverge: a season that’s profitable on paper can still leave you short in February if the cash wasn’t set aside, which is why the plan manages the two separately. Light snow work is never counted on. The season has to fund the whole year.
Management
Through the startup stage, Evan is the owner, operator, salesperson, and route manager. That’s deliberate.
Running the route himself is how he learns which neighborhoods pay best, which add-ons sell, and why customers stay or leave before training anyone else to mow on Meadowline’s name.
His experience is the qualification: nine years on commercial crews, the last four as a crew lead handling routing, quality, and a small team. He already knows how to run a route efficiently, price a job to make money, and manage a helper.
Bookkeeping and taxes go to an outside professional. The only planned hire is a seasonal part-time helper in the peak weeks of Years 2 and 3. That help is there to do the work, not to sell or manage; Evan stays responsible for route quality and customer communication for as long as the business runs a single route.
Financial Plan
Every decision above shows up in the numbers. Revenue is volume-driven, built as mowing visits times price plus the add-on programs, not guessed as a share of a market total.
Equipment is depreciated straight-line over five years on the basis in IRS Publication 946. All figures are pre-tax, because the single-member LLC passes income through to the personal return.
Startup Costs
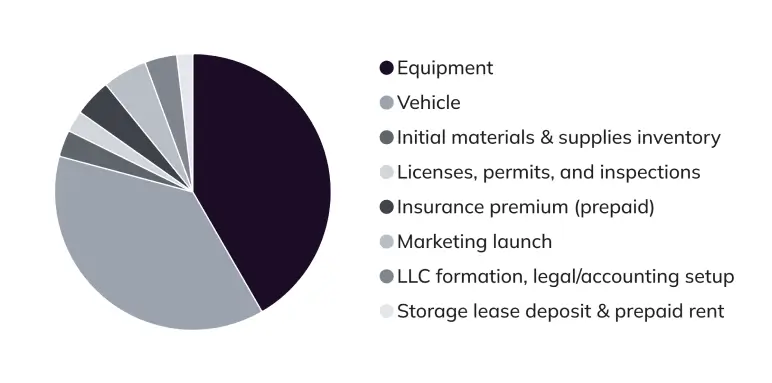
| Expense | Amount |
|---|---|
| Equipment (commercial zero-turn mower, handhelds, trailer) | $20,000 |
| Vehicle (used half-ton pickup truck) | $18,000 |
| Initial materials & supplies inventory | $1,500 |
| Licenses, permits, and inspections | $1,200 |
| Insurance premium (prepaid) | $2,100 |
| Marketing launch (branding, website, signage) | $2,500 |
| Professional services (LLC formation, legal/accounting setup) | $1,800 |
| Storage lease deposit & prepaid rent | $900 |
| Working capital reserve (cash) | $27,000 |
| Total startup costs | $75,000 |
Source of Funds
| Source | Amount |
|---|---|
| SBA-backed term loan (Cedar Hollow Community Bank) | $55,000 |
| Owner equity contribution (Evan Carter) | $20,000 |
| Total startup capital | $75,000 |
Financial Assumptions
| Item | Assumption |
|---|---|
| Average price per mowing visit | Year 1: $50; Year 2: $52; Year 3: $55 |
| Mowing visits (annual) | Year 1: 1,350; Year 2: 2,600; Year 3: 3,500 |
| Active recurring accounts (year-end) | Year 1: 55; Year 2: 95; Year 3: 125 |
| Annual account renewal | ~85% |
| Implied revenue growth (volume-driven) | Year 2: +98% (first full season); Year 3: +42% |
| Direct materials (fertilizer, seed, blades, line) | 12% of revenue |
| Direct labor (seasonal part-time helper) | $18/hr; 300 / 700 / 1,100 hrs |
| Payroll tax rate (FICA) | 7.65% on direct labor and owner salary |
Loan Assumptions
| Item | Assumption |
|---|---|
| Loan amount | $55,000 |
| Term | 84 months |
| Fixed interest rate | 9.5% |
| Monthly payment | $899 |
| Annual debt service | $10,787 |
| Year 1 interest | $4,976 |
| Year 1 principal repayment | $5,811 |
| Year 2 interest | $4,402 |
| Year 2 principal repayment | $6,385 |
| Year 3 interest | $3,752 |
| Year 3 principal repayment | $7,035 |
| Loan balance after Year 3 | $35,769 |
The loan is used for productive assets and working capital rather than to support a large permanent payroll.
Depreciation Schedule
| Asset | Cost | Life | Annual dep. |
|---|---|---|---|
| Used half-ton pickup truck | $18,000 | 5 yr | $3,600 |
| Commercial zero-turn mower | $11,000 | 5 yr | $2,200 |
| Trailer | $5,000 | 5 yr | $1,000 |
| Handheld equipment (trimmers, blowers, edger, backup mower) | $4,000 | 5 yr | $800 |
| Total | $38,000 | — | $7,600 |
Income Statement (Profit & Loss)
| Item | Year 1 | Year 2 | Year 3 |
|---|---|---|---|
| Mowing visits (annual) | 1,350 | 2,600 | 3,500 |
| Mowing revenue | $67,500 | $135,200 | $192,500 |
| Seasonal add-on revenue | $36,000 | $70,000 | $100,000 |
| Total revenue | $103,500 | $205,200 | $292,500 |
| Direct materials (12%) | $12,420 | $24,624 | $35,100 |
| Direct labor (seasonal helper) | $5,400 | $12,600 | $19,800 |
| Payroll taxes on direct labor (7.65%) | $413 | $964 | $1,515 |
| Total COGS | $18,233 | $38,188 | $56,415 |
| Gross profit | $85,267 | $167,012 | $236,085 |
| Gross margin | 82.4% | 81.4% | 80.7% |
| Owner salary | $36,000 | $55,000 | $72,000 |
| Owner payroll taxes (7.65%) | $2,754 | $4,208 | $5,508 |
| Equipment storage rent | $3,600 | $3,600 | $6,000 |
| Insurance | $4,200 | $5,400 | $6,800 |
| Accounting & bookkeeping | $1,800 | $2,400 | $2,400 |
| Phone & internet | $1,200 | $1,200 | $1,440 |
| Ongoing marketing | $3,000 | $4,500 | $6,000 |
| Fuel & vehicle | $4,800 | $8,400 | $11,500 |
| Supplies & consumables | $1,500 | $2,600 | $3,600 |
| Equipment maintenance & repairs | $1,200 | $2,400 | $3,200 |
| Technology subscriptions (routing, invoicing) | $1,200 | $1,500 | $1,800 |
| Marketing launch (one-time) | $2,500 | — | — |
| Licenses & permits (one-time) | $1,200 | — | — |
| Professional services (one-time) | $1,800 | — | — |
| Total operating expenses | $66,754 | $91,208 | $120,248 |
| EBITDA | $18,513 | $75,804 | $115,837 |
| Depreciation | $7,600 | $7,600 | $7,600 |
| EBIT | $10,913 | $68,204 | $108,237 |
| Interest expense | $4,976 | $4,402 | $3,752 |
| Net income (pre-tax) | $5,937 | $63,802 | $104,485 |
Cash Flow Statement
| Item | Year 1 | Year 2 | Year 3 |
|---|---|---|---|
| Beginning cash | $32,500 | $38,822 | $99,979 |
| Net income (pre-tax) | $5,937 | $63,802 | $104,485 |
| Depreciation (non-cash) | $7,600 | $7,600 | $7,600 |
| Change in accounts receivable | ($4,253) | ($4,180) | ($3,588) |
| Change in inventory | $0 | ($500) | ($500) |
| Change in accounts payable | $749 | $820 | $749 |
| Change in prepaid expenses | $2,100 | $0 | $0 |
| Net cash from operations | $12,133 | $67,542 | $108,746 |
| Loan principal repayment | ($5,811) | ($6,385) | ($7,035) |
| Net change in cash | $6,322 | $61,157 | $101,711 |
| Ending cash | $38,822 | $99,979 | $201,690 |
Opening Balance Sheet (at launch)
| Line item | Amount |
|---|---|
| Cash (working capital reserve + one-time expense float) | $32,500 |
| Inventory | $1,500 |
| Prepaid rent & insurance | $3,000 |
| Gross PP&E | $38,000 |
| Total assets | $75,000 |
| Term loan | $55,000 |
| Owner’s capital (paid-in) | $20,000 |
| Total liabilities + equity | $75,000 |
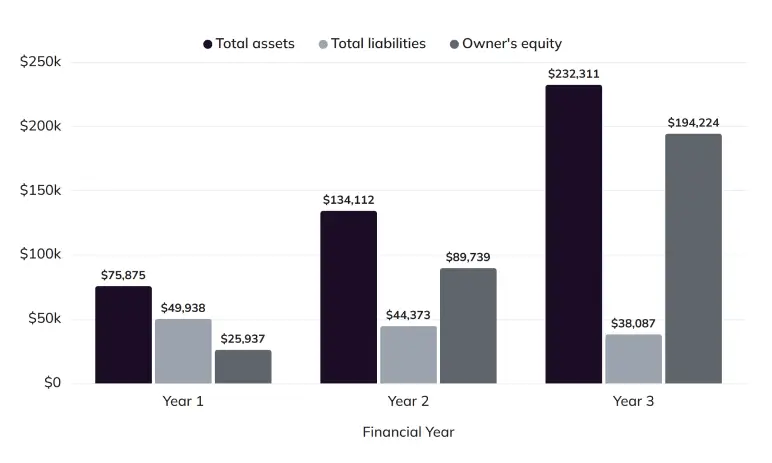
Balance Sheet (Years 1 to 3)
| Item | Year 1 | Year 2 | Year 3 |
|---|---|---|---|
| Cash | $38,822 | $99,979 | $201,690 |
| Accounts receivable | $4,253 | $8,433 | $12,021 |
| Inventory | $1,500 | $2,000 | $2,500 |
| Prepaid expenses | $900 | $900 | $900 |
| Net PP&E | $30,400 | $22,800 | $15,200 |
| Total assets | $75,875 | $134,112 | $232,311 |
| Accounts payable | $749 | $1,569 | $2,318 |
| Term loan | $49,189 | $42,804 | $35,769 |
| Total liabilities | $49,938 | $44,373 | $38,087 |
| Paid-in capital | $20,000 | $20,000 | $20,000 |
| Retained earnings (cumulative) | $5,937 | $69,739 | $174,224 |
| Owner’s equity | $25,937 | $89,739 | $194,224 |
Break-Even Analysis
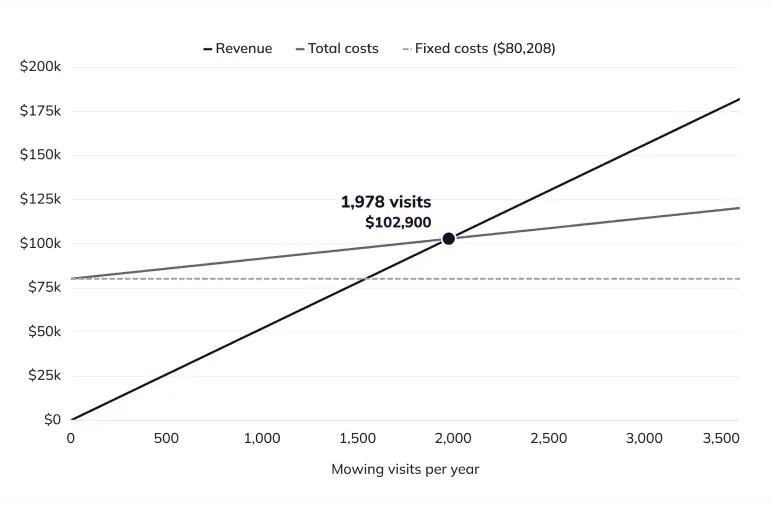
| Item | Value |
|---|---|
| Average revenue per mowing visit | $52 |
| Total variable cost per visit | $11.45 |
| Contribution margin per visit | $40.55 (78.0%) |
| Annual fixed operating costs (Yr 2 steady-state) | $80,208 |
| Break-even visits per year | 1,978 |
| Break-even visits per operating month (~8-mo season) | ~247 |
| Break-even revenue (annual) | $102,900 |
The Quickest Way to turn a Business Idea into a Business Plan
Fill-in-the-blanks and automatic financials make it easy.

Frequently Asked Questions
What should be included in a lawn care business plan?
How to secure financing for a lawn service business?
What is the difference between a lawn mowing and a lawn maintenance business plan?
Do I need a business license for my lawn service business?
Where can I find a lawn care business plan sample?
Upmetrics
Upmetrics is the #1 business planning software that helps entrepreneurs and business owners create investment-ready business plans using AI. We regularly share business planning insights on our blog. Check out the Upmetrics blog for such interesting reads. Read more